1/10/26 Prices
The US markets fell away on US centric data last night. It’s a little hard to see how this data wasn’t predictable given the reporting system in the US, but hey, the bulls need feeding every day right. Corn futures fell sharply, weighing on all grains at Chicago. The punters “were not expecting” US corn stocks to be as high as they are, a 35% year on year increase is substantial. After last years record crop I’m wondering why this came as big surprise though.
The move lower in futures of this magnitude does look like a bit of knee jerk reaction to finding an extra 4.4mt of US corn. There’s still a whole bunch of issues to pull through, poor French crop, limited Ukraine exports, these are not minor issues.
The report confirmed the US harvested their smallest wheat crop in over 50 years. The USDA numbers did come in a little better than the trade estimates leading up to the report, but were not that different to the August estimates. That leaves the move in US wheat futures mainly being seen as spillover pressure from the corn pit. The punters are probably taking the opportunity to adjust what was probably an over priced US wheat market. Current values were based of an increase in US exports due to restrictions out of the Black Sea, this expected increase in US wheat exports, to date, has not occurred.
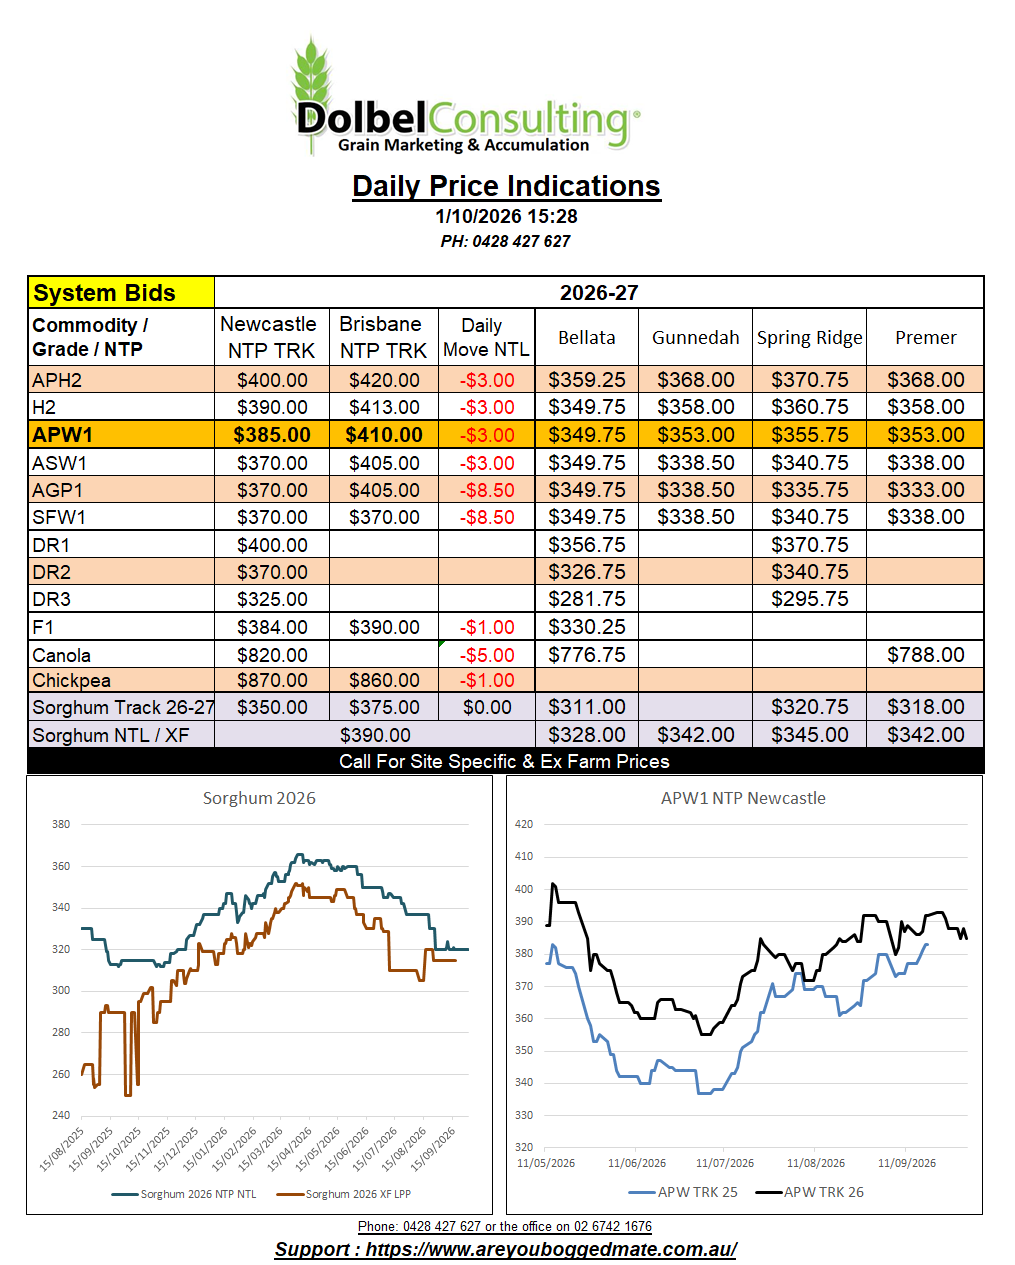
Delhi chickpeas were higher again overnight, the average closing value delivered Delhi market came in around 7058Rs/Q. Combine this with a softer Aussie dollar are we see the day to day conversion comparison increasing by roughly AUD$18.41/tonne. What a couple of weeks it has been for chickpeas.
The trade are suggesting good demand is coming from both Pakistan and Bangladesh is key driver. Locally we may also be seeing some supply issues for the last of the old crop. Combine this with a smaller Canadian crop that has sat through a less than ideal harvest period. Then add a poor monsoon result for India across much of the chickpea region, not ideal for stored soil moisture or irrigators, and we start to see why local and Indian values have climbed by more than $150/t since the end of August.