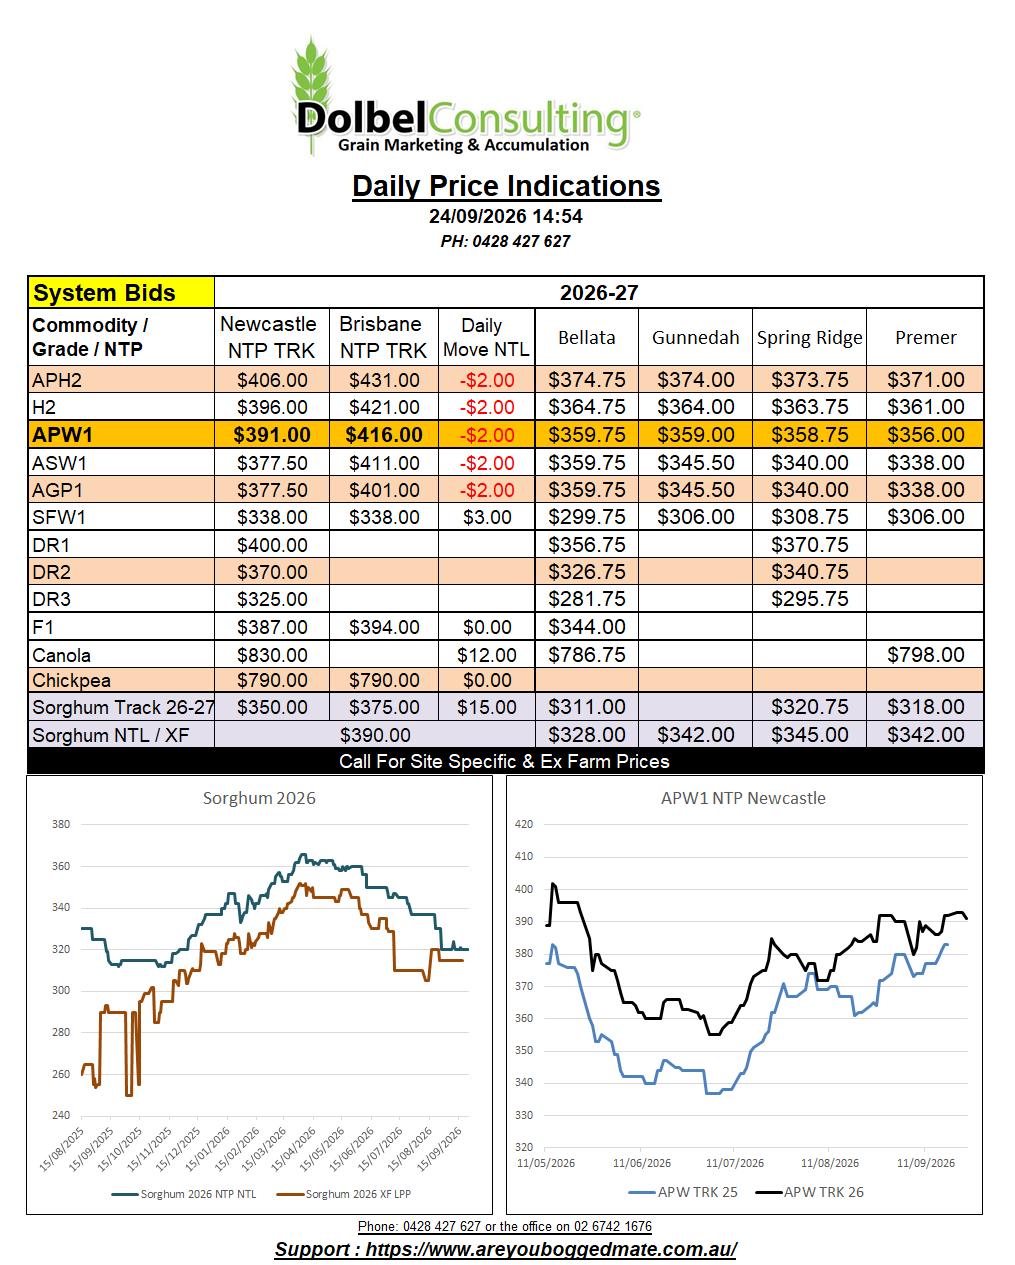
24/9/26 Prices
It’s all about the Aussie dollar this morning, back 1.19% against the US dollar, and lower against most of our major trading partners. The move in the AUD was worth roughly +AUD$4.41/t tonne, all but countering the -AUD$4.57/t move lower in Chicago Dec SRWW futures.
Looking at the day to day conversion comparisons for many international wheat values, we see the weaker AUD has countered most every decline bar the fall in HRWW values out of the Pacific Northwest. Although cheaper now, US HRWW out of the PNW is still over US$5.50/t more expensive than Aussie H2 grower bids into NE Asia.
Maybe we just got lucky. Private sector improvements in the US helped the USD higher. In the case of the Australia reports indicate the exact opposite, a decline in the private sector. Year on year the Australian private sector still shows a slight expansion, I don’t know where, maybe in NDIS providers, or accountants and lawyers handling bankruptcies. I know it ain’t in the retail or grain trade sector. The big question is, will this be enough to save us from a 25pt rate rise next week. The punters have the RBA and the FED upping rates by 25pts next week. If the RBA was to fall out of step with the FED, we would most likely see a sharp drop in the AUD against the USD. We can only hope. With the FED holding a large amount of US treasury bonds the US rate rise has to be odds on.
The punters had been talking a record durum harvest in Tunisia, this now appears optimistic. Harvest data is coming in and the crop is now 90% in the bin. The ODC (Office des Cereales), the state owned agency responsible for grains, has taken in 810kt of durum, 20kt less than last year. This does point to Tunisia again being a net importer of durum in 2026-27.
Overnight we’ve seen both Canadian and French durum wheat conversions improve, some AUD driven improvement, better FOB origin too for France.