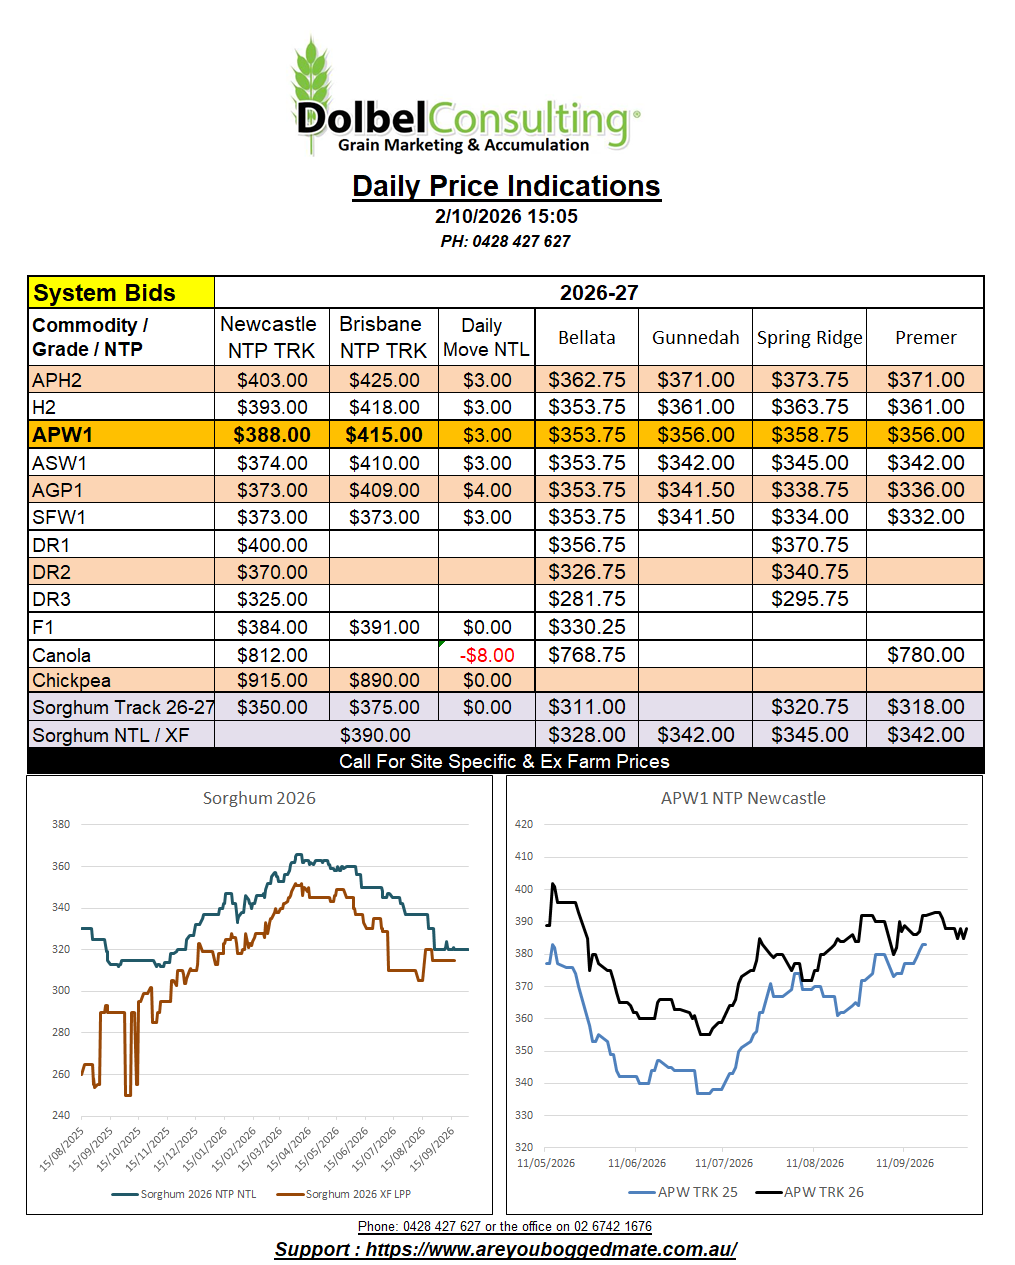
2/10/26 Prices
US grain export sales remain modest. Soybeans came in over the higher end of expectation, 1.034mt is a good effort. Much better than wheat at 289kt and corn at 536kt. Sales don’t equate to loadings though, so the market generally takes less notice of the sales number than it does of the export loadings number.
The soybean number is good, but wasn’t good enough to offer spillover support to Canadian canola values. Cash bids for a Dec pickup XF SE Saskatchewan averaged a fall of CAD$14.68/t overnight. Converted Canadian values gives us a C&F Europe value of something close to US$670 / tonne for GM canola. This is pretty much bang on the same C&F value for Aussie Non GM canola C&F Europe.
Canadian canola harvest has progressed to about 45% complete, spring wheat is now about 65% harvested, and durum is about 79% off. Chickpea harvest is estimated to be about 65% compete as of September 28th.
World Ag Weather confirms the last 7 days have been mostly dry across Saskatchewan and Alberta, allowing those that could get back into fields to recommence harvest operations. With the next 7 days expected to remain dry we should see those that couldn’t access fields over the last 7 days get back into the paddock. This will allow the trade to better understand the extent of the weather damage to the Canadian spring sown crops. Parts of western Saskatchewan are already seeing frosts, this is limiting harvest hours per day. Days did warm quickly last week and pushed into the high 20’s and low 30sC. This will change next week, with much cooler conditions being forecast during the day.
There’s been useful falls across much of central Russia, but the upper reaches of the Volga Valley appear to be missing good falls. The forecast if for a mostly dry week ahead. This will allow winter crop sowing to progress in the west. There’s still a lot of speculation on how much wheat Russia will sow.