7/10/26 Prices
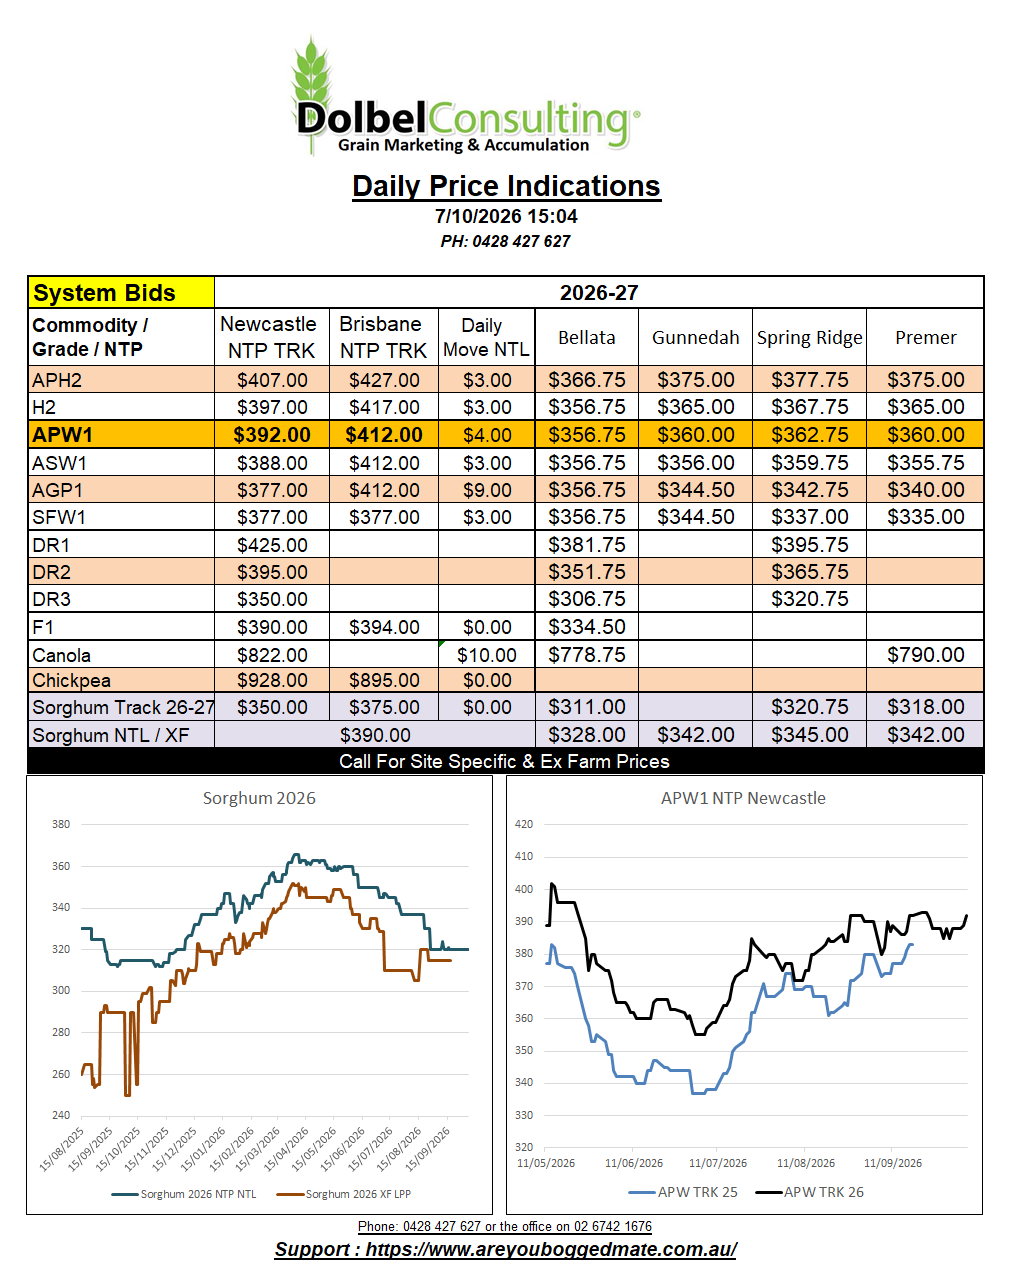
Some nice moves higher on most grain futures last night. Chicago soybeans were the clear winner, up 21.75c/bu (AUD$11.44/t) in the November slot. Wheat and corn futures at Chicago had double digit gains in c/bu, and Paris milling wheat closed in the green, up €2.25/t in the December contract.
Paris rapeseed futures were also higher, bar the front month, which is nearing expiry. The Paris November rapeseed contract was down sharply, shedding €15.25/t. Ignoring that, the remaining months were up between €2.00 and €3.50/t, the Feb 27 rapeseed slot closing €2.25/t higher.
International cash wheat bids were firmer for most origins, bar the Black Sea, which was flat to softer. Hard red winter wheat out of the US Pacific Northwest followed the US futures market higher. The day to day conversion comparison for PNW HRWW is up roughly AUD$6.57/t, a little more than the improvement in spring wheat, which was up AUD$5.03/t. Canadian spring wheat was firmer, FOB PNW by AUD$6.71/t.
International canola and rapeseed values also pushed higher, aided by the nice close in Chicago soybeans. The move in beans was triggered by a number of things, but the most obvious is the slow progress in the US harvest and some questions are open on US quality. China also picked up a few tonnes of US soybeans.
Comparing both Canadian and Aussie canola at current values C&F Europe, indicates that both options are at very similar in value. We had, in the recent past, been able to extract an obvious premium for Australia canola of anything between US$20 and US$40 per tonne for Australian product.
Australian canola production is very good this year, a possible record. Canadian production although very good, may have a few quality issues. It will be interesting to see if Australian canola can, in time, demand the premium it once could into the Non GM EU market.
International feed barley values were on average flat to a smidge lower. More feed wheat by some production regions may weigh on this market over time.