12/11/26 Prices
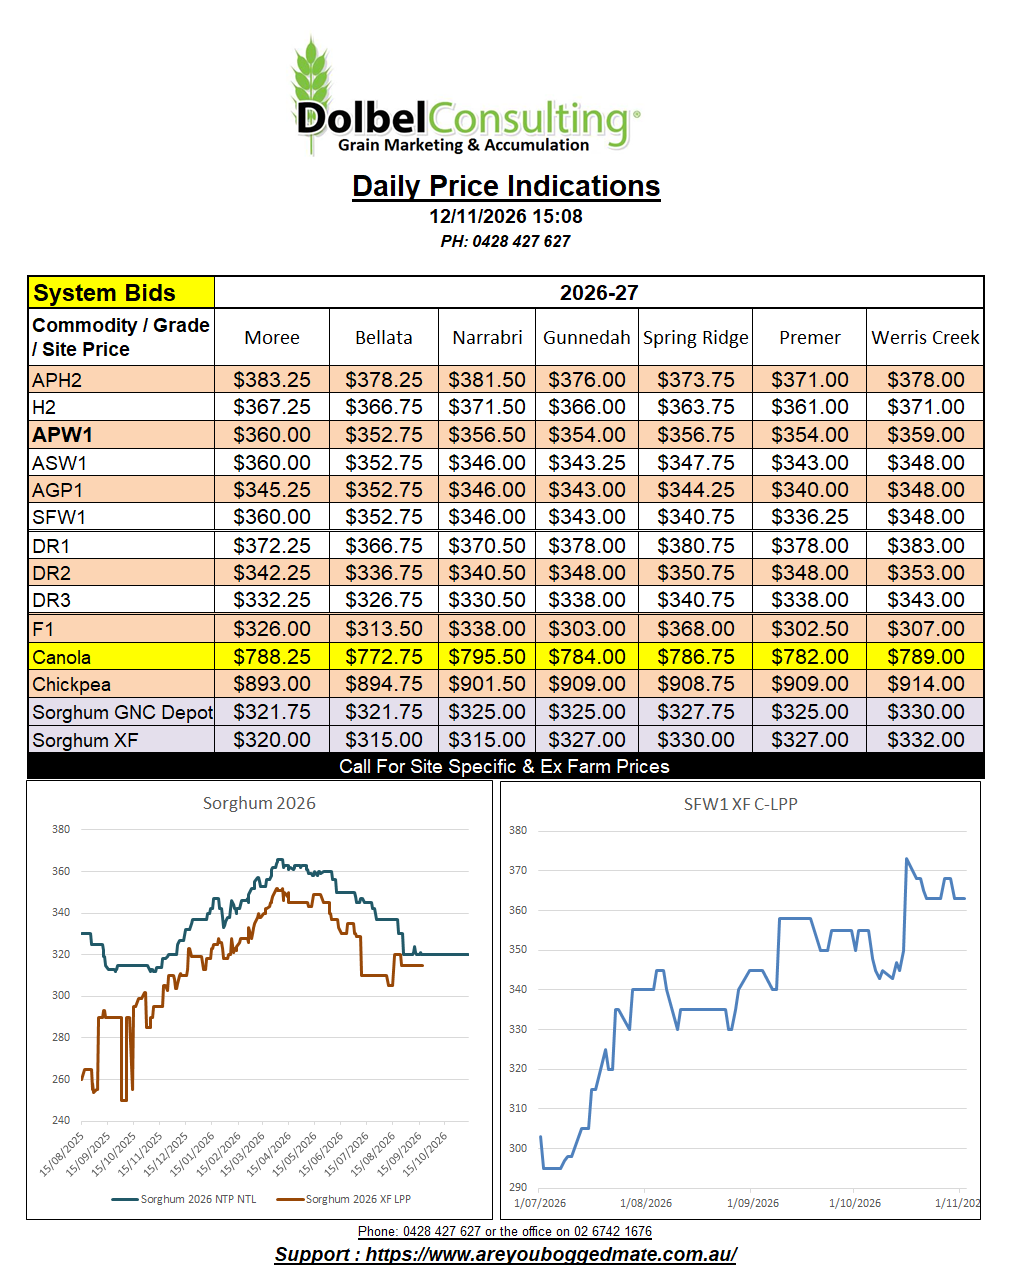
Mostly green on the screen this morning. Chicago corn was weaker across all months, spoiling the illusion that the market was poised to bounce. There were some higher moves in US wheat futures though. Futures for hard red winter wheat at Chicago gained 5.25c/bu (AUD$2.81/t) in the Dec slot. This rolled across the FOB values out of the Pacific Northwest. HRWW there gaining roughly AUD$4.00/t compared to yesterdays conversions.
Paris rapeseed futures are the biggest winner overnight. The Feb slot there gaining E12.50/t, surprising many. Canada has a public holiday on remembrance day, so no fresh data out of ICE Winnipeg this morning.
The move higher in Paris equates to a day to day change of the conversion comparison of AUD$16.49/t. Local markets have continued to track the Paris rapeseed contract for canola. If this continues today it should offer local producers a spike and a marketing opportunity for those looking to sell.
Russian / Ukraine piece talks were probably thwarted somewhat by attacks on the Russian Baltic port of Ust-Luga, about 80ks SW of St Petersburg. This port area is primarily an energy export hub. Since the closure of many Black Sea ports, Russian wheat has been moving out of the Baltic ports. It’s believed that the target was the oil and gas infrastructure, and that the wheat export facilities were undamaged.
EU soft wheat exports since July are sitting at roughly 10.05mt as of November 8th. This is above the same period last year when 9.69mt had been shipped. One may have expected to see a larger than 360kt increase over the last 4 months given the Black Sea issues. There are a number of punters that are accusing the EU of publishing lower than actual export data though. The conspiracy theorist in me thinks we may see adjustments when “needed”. Like if we were to see a Black Sea corridor deal… maybe. The EU has even confirmed French & Bulgarian data has been incomplete for some time.