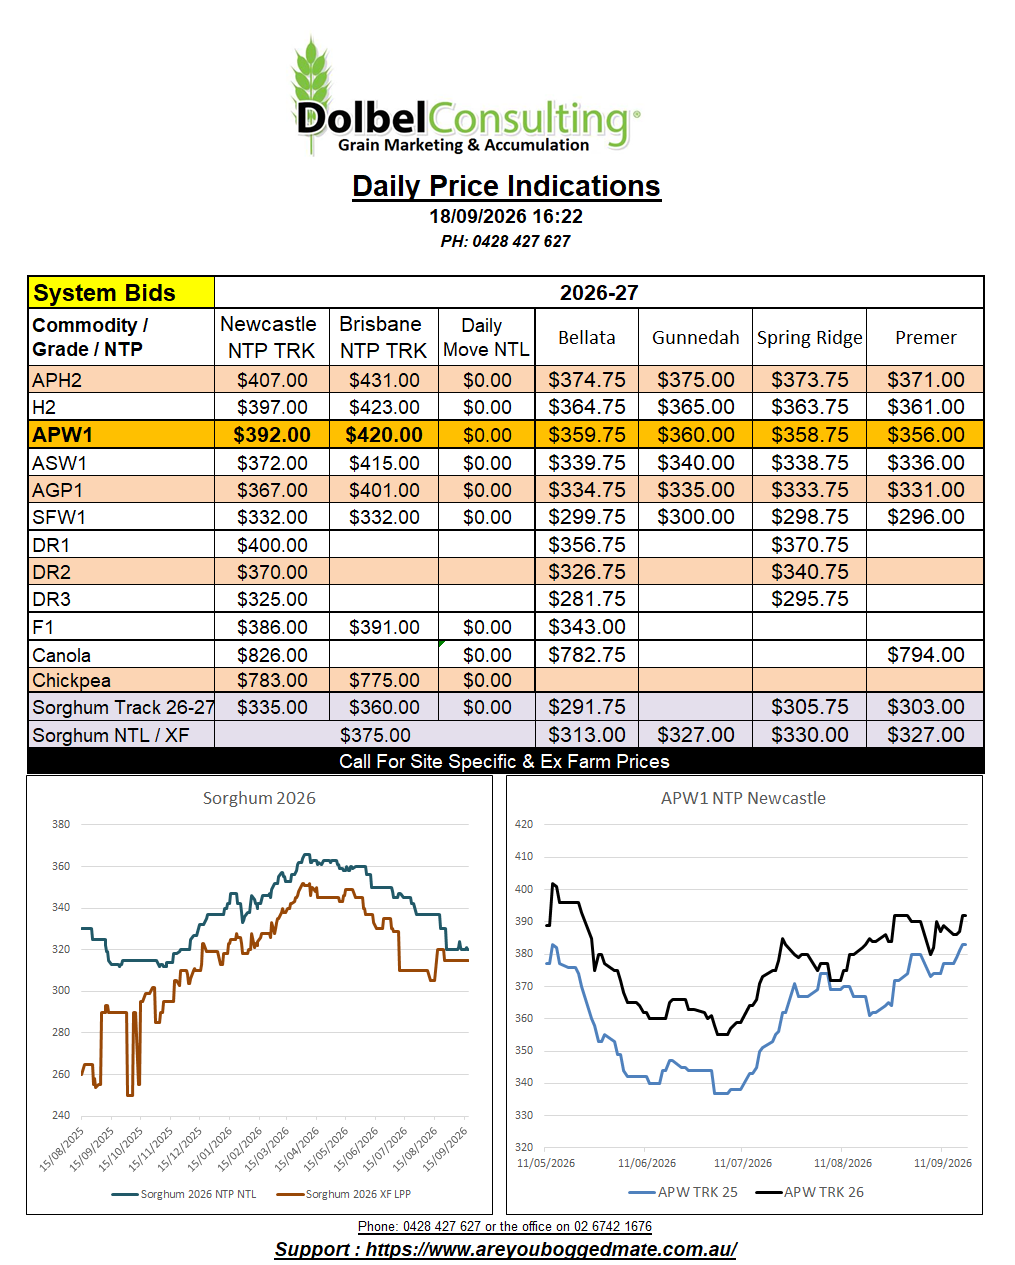
18/9/26 Prices
Pakistan received offers for 656kt in their tender, lowest price was US$348.83/t and the highest was US$369.95 C&F. Let’s call the average US$350 for the sake of the comparison exercise. I’ve attached a international map showing FOB origin values, ocean rates and C&F values.
The exercise is pretty crude but tends to highlight a few things. US wheat is expensive, Aussie wheat off the west coast is not. There is basically little reason for Aussie wheat to track US values lower dollar for dollar unless US values fall by a significant amount.
It also highlights just how competitive French wheat is against Romanian wheat. One thought that comes to mind is what is cheapest FOB Romania. Is it Romanian wheat or is it Ukrainian wheat. Currently we see Ukraine wheat values at roughly US$214 FOB Odessa. Lets take a rough estimate off that to get it to an upcountry price, say -US$25.00 (not much), so US$189 up country. That leaves US$142 (AUD$200) to get that wheat down to Romania and onto a boat. Say that wheat is located in central, SE Ukraine, about 750ks by road to Constanta port in Romania. That’s driving past the Danube ports.
I’m not saying a trader may make more money buying Ukraine wheat and executing it out of Conastanta, while Odessa is closed, than what they would have been making prior to the closure out of Odessa, but I’d really like to see the actual math behind this theory.
Showers are easing across the Canadian Prairies and the forecast is for a dry week ahead. We should start to see some reliable quality reports for spring wheat, durum and canola hit the market next week. Overnight Winnipeg canola futures moved higher. The Jan27 contract up CAD$6.30/t. This is against the flow in both Chicago soybeans and to a lesser extent Paris rapeseed futures. Paris more closely reflecting the move in crude oil. Comparing Canadian and Aussie canola values C&F Europe, tends to show that both origins are now pretty much the same price. So much for the non GM premium ?
International wheat values were less volatile than the US product. One may expect to see some further downside in US values short term.