22/9/26 Prices
It’s a sea of green across international futures this morning.
Apart from crude oil, it’s back sharply, we’ll be looking at $2.00/litre petrol in no time. WTI crude is back US$4.81/b in the Oct slot and Brent is back US$3.83/b in the Nov slot. Surely it no longer smells like inflation to the RBA ????
A US Admiral was quoted as saying the crude oil and LNG flows out of the Straight of Hormuz were the highest they have been over the last two weeks, during the past six months.
China featured well on the US weekly soybean export inspections report, picking up 447kt of the 759kt total. The trade are pretty sure that Xi will announce further large purchases when he visits the US this week. Smells like buy the rumour / sell the fact to me, but hey, take what you can.
Chicago wheat futures took back pretty much what they lost on Friday. Weekly export loading for the US were down 29.12% from the previous week at just 335kt. The US marketing year total shipments for wheat sits at 6.028mt, roughly 31.5% below the same time last year….. move along, nothing to see here. Funds are now net short Chicago wheat.
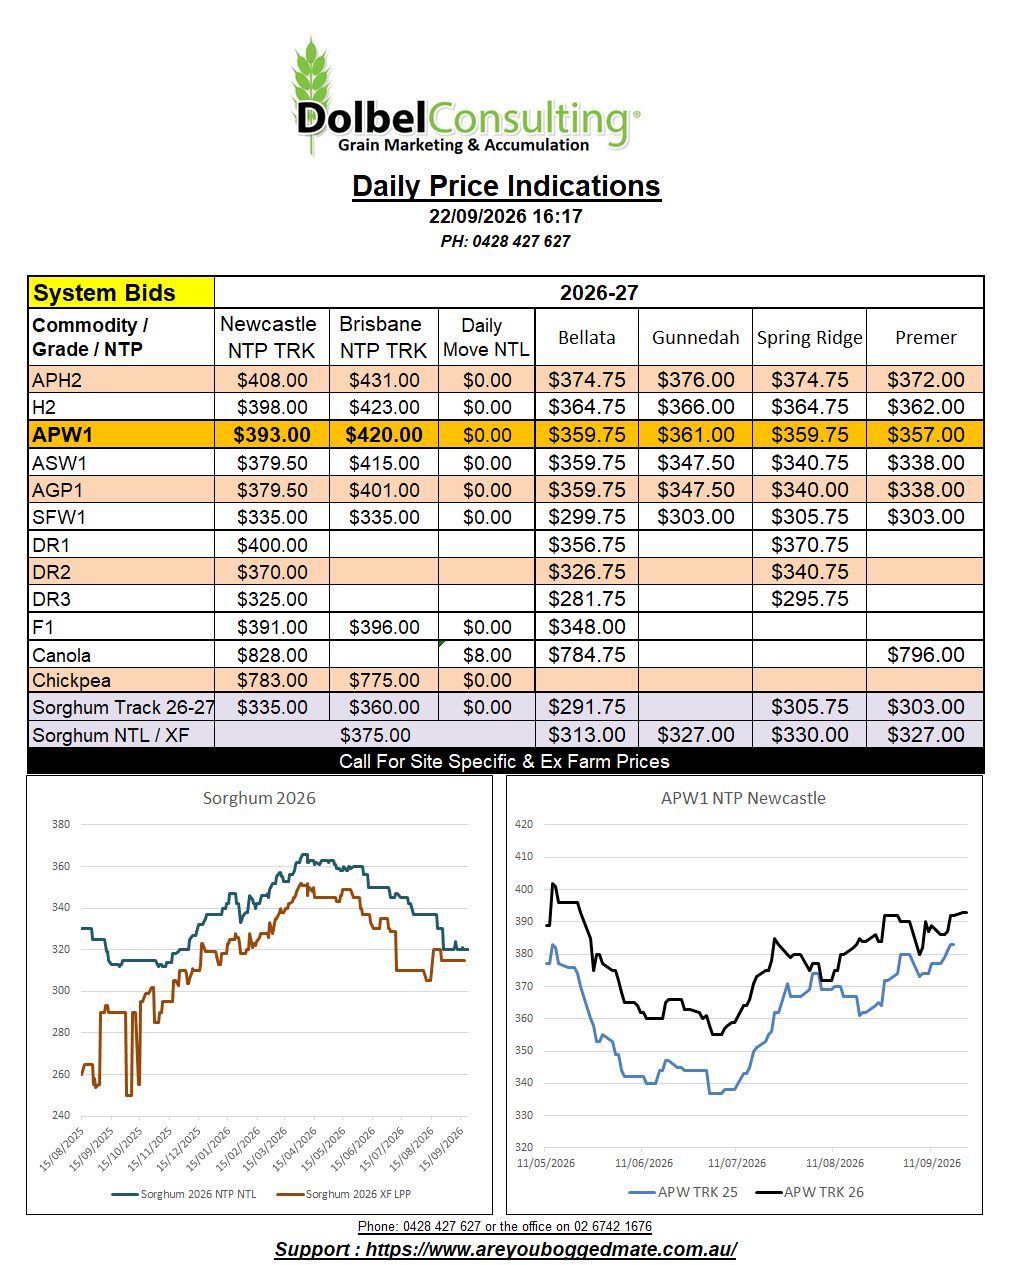
Paris milling wheat was dragged along for the ride, up E2.25/t in the Dec slot. There were good moves in canola and rapeseed. Paris rapeseed futures closed E5.25/t higher in the Feb slot, Winnipeg canola was up CAD$13.80/t in the Jan slot. Comparing these moves to the conversions to AUD/t on Fridays values, we see a net change of +AUD$8.80/t in Paris and +AUD$16.84/t at Winnipeg. The move in Canadian values keeps their product bang on par with the Aussie product C&F France. French values FOB Rouen tend to indicate that there’s still a little fat in it for the trade at these levels too. Possibly meaning that the trade should have no problem tracking the Paris market higher if they can find buyers, possibly establishing a non GM premium to Canadian product.
International sorghum values followed the corn market in the States higher. Good weekly US corn exports helped the feed grain complex strengthen.