8/10/26 Prices
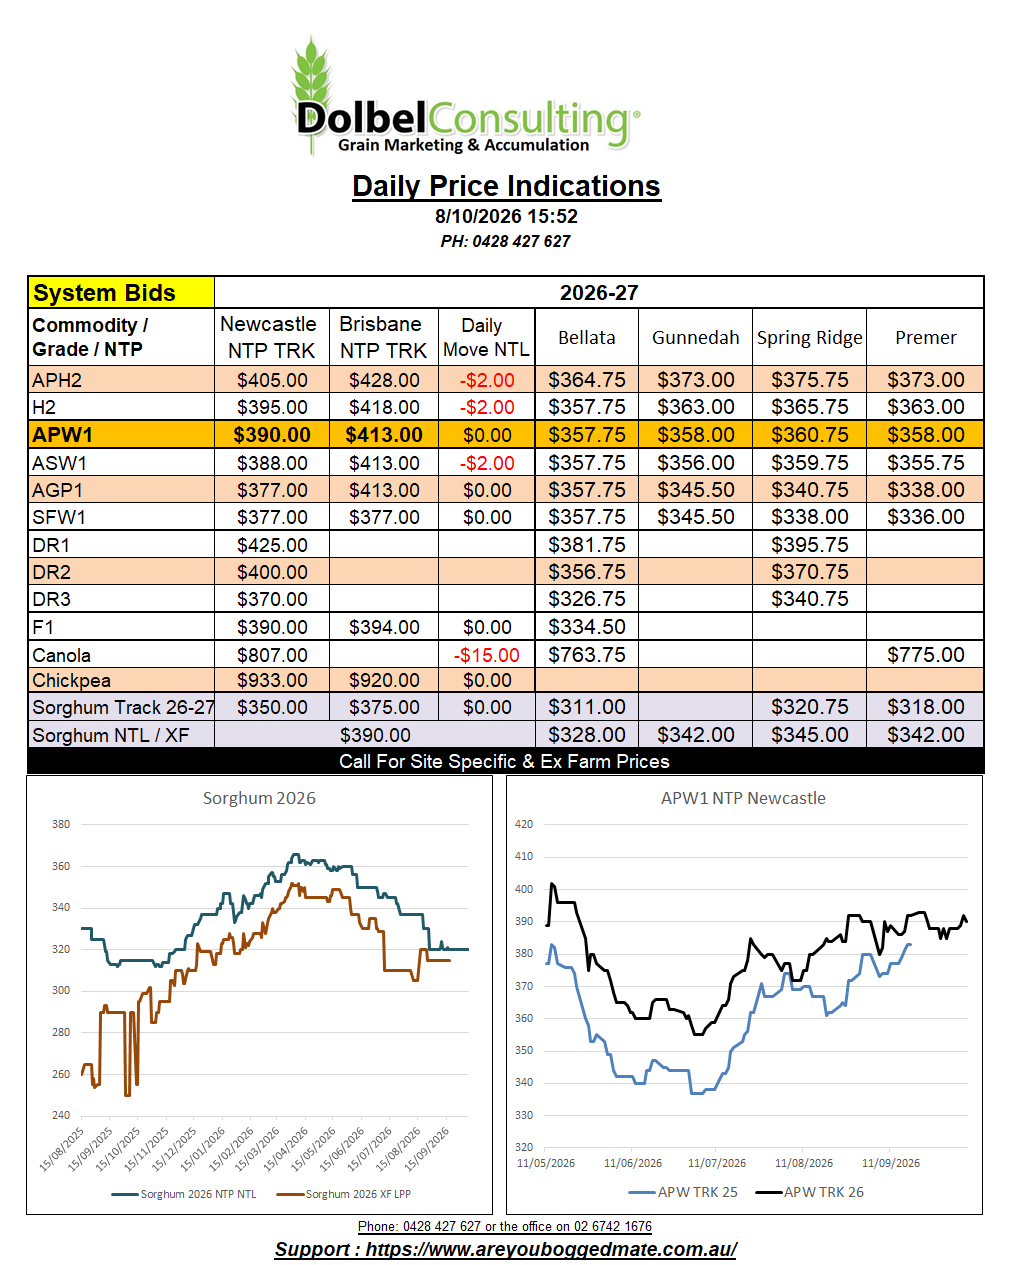
There’s a lot of red on the screen this morning. Chicago wheat futures were hit hard, HRWW and SRWW suffering double digit losses. MGEX spring wheat followed, not hit as hard, but shedding most of the previous sessions gains.
As mentioned yesterday, managed money is long wheat, probably not by as many contracts this morning as what they were on Monday. We have a USDA World Ag Supply and Demand Estimates report out on Friday night our time. Was last nights move simply a little nervous positioning ahead of this report, some profit taking while it’s on the table. Time will tell.
Fundamentally the world of wheat isn’t terribly bearish at present. We have Ukraine back to bombing ships in the Black Sea and Russia energy infrastructure. We have winter wheat sowing delays in both the US and Russia. The Russian farmer must be wondering do they even bother at this stage. Alternative shipping routes for Black Sea wheat are already jammed trying to move old crop, at half the volume the Black Sea can, this could persist for months.
Over the last week much of the US winter wheat belt has seen too much rain to get into fields. Some parts of Kansas and Oklahoma have picked up 75-100mm of rain over the last 7 days, add that to roughly the same amount the previous week and yes, it’s very wet. Will a week of dry weather that is expected to come to a halt in a few days be enough to see some sowing progress in next Tuesdays crop progress report, some doubt it.
The Delhi chickpea market broke the trend set by US and EU grain futures. The average Delhi market price gained roughly 117Rs/Q, closing at an average value of about 7501Rs/Q. The last time the Delhi market was around this number was back on October 14th 2024. Back then we had an exchange rate of 56.519Rs/AUD, today that is closer to 67.392 Back then the local bid was at $975. Taking that currency difference into account current bids are not that bad. Local bids did top out at just over $1000 in 2024.