12/10/26
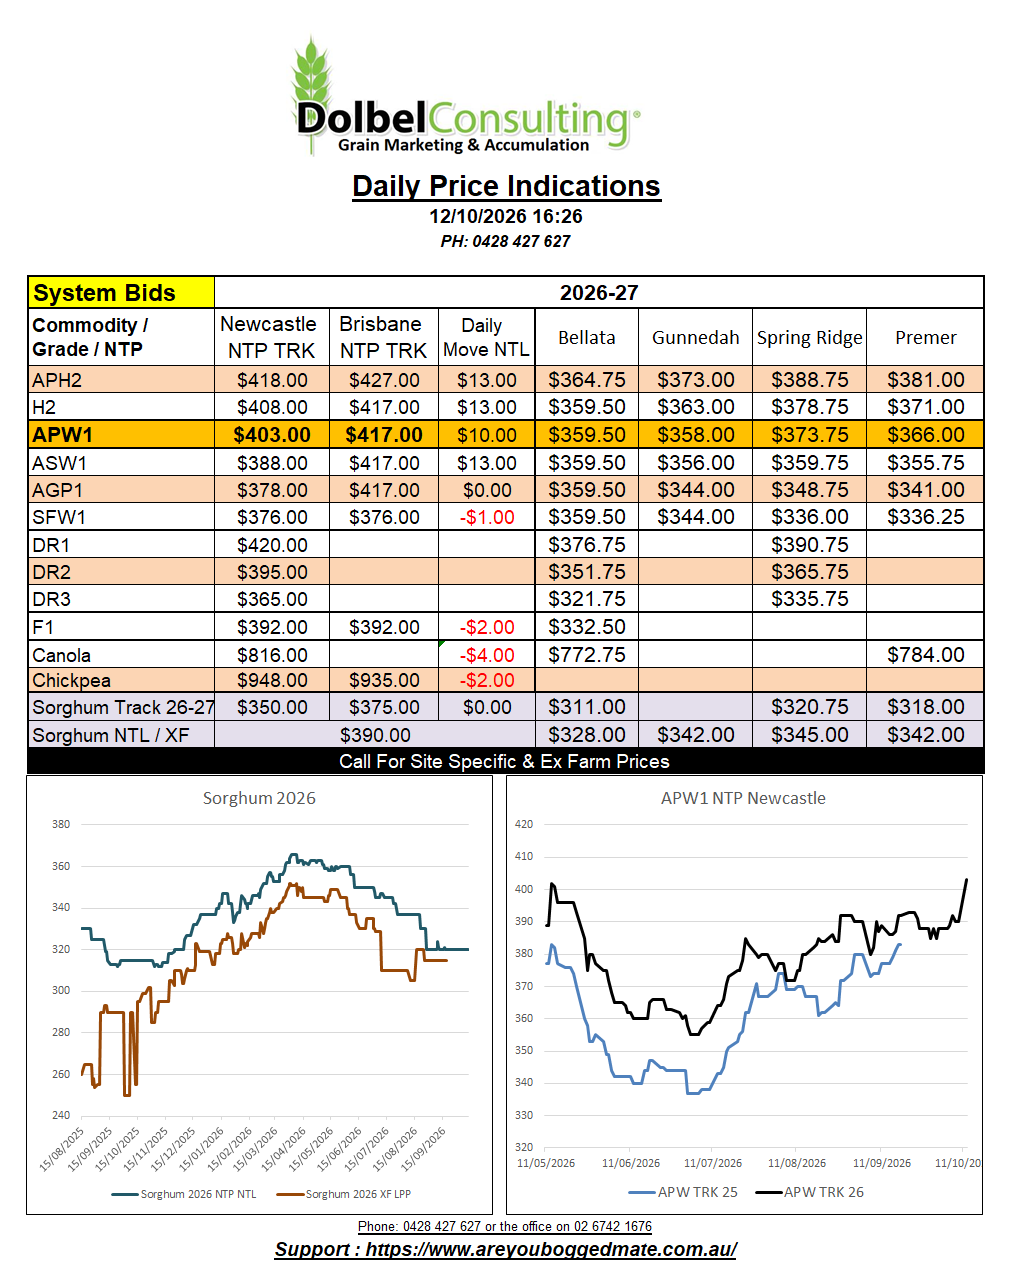
It was USDA World Ag Supply and Demand Estimates report night, last night. So we’ll drill down into the WASDE a little this morning.
You might assume that since US wheat futures are sharply lower this morning that the WASDE was bearish wheat. Well, from the outside looking at wheat and wheat only, one could argue that point on this data pretty easily.
So let’s clear up what has killed the market first. Basically spillover selling from US corn data is the culprit. The USDA raised average corn yields by 2.7bpa (0.169t/ha), although not looking like a huge amount, it was the largest Sept – Oct increase in a WASDE report since 2005. The nail in the coffin was the 11bpa increase to Nebraska. A state that had seen too little rain throughout much of the growing season, and then too much rain at maturity. The punters will argue about this report for years to come.
Back onto wheat. Wheat seems to be the bystander at the pub fight. Just there minding their own business, prior to getting hit in the face by a bar stool. Will it correct next week, maybe, maybe not. The US HRWW product was a little expensive compared to a bunch of alternatives. The question is how much will those alternatives move on Monday due to the fall in US wheat futures. The move lower in HRWW cash values out of the US Pacific Northwest now puts Aussie H2 grower bids at about a US$10.00 premium to HRWW C&F Asian consumer. The 2025-26 crop saw a US$20-US$25 premium over HRWW not having a huge impact on Aussie export sales. That does tend to indicate that the Aussie white wheat premium does exist to a degree, well at least while the Black Sea burns.
Some data. World wheat ending stocks fell 250kt, to 276.04mt, still too much. Mind you China own 119.2mt of that and India own 29.5mt of it. Major exporter ending stocks increased, mainly due to slow Russian exports, back 3mt to 40mt. The USDA increased Aussie carry in by 750kt, this rolled across the board as an increase in Aussie ending stocks. Lower production in Brazil, rolled across to better Argie exports, countering some of the Aussie increase. Canadian production was increased, big call considering the weather damage. The USDA increased Canadian exports by 500kt, countering the production increase.