15/10/26 Prices
Remember the good old days when they wanted to destroy data they’d just fly a plane into it. Not anymore, it’s a new age, now they fly a drone into a data centre and poof, it’s all gone….. Yeah, I’ll peel off the tin foil hat now and get back into the grain market.
Chicago corn and wheat futures appear to be consolidating around the current values. We still haven’t seen the big up tick in exports for US wheat as the US pick up the slack from the Black Sea, but one does get the feeling it’s coming.
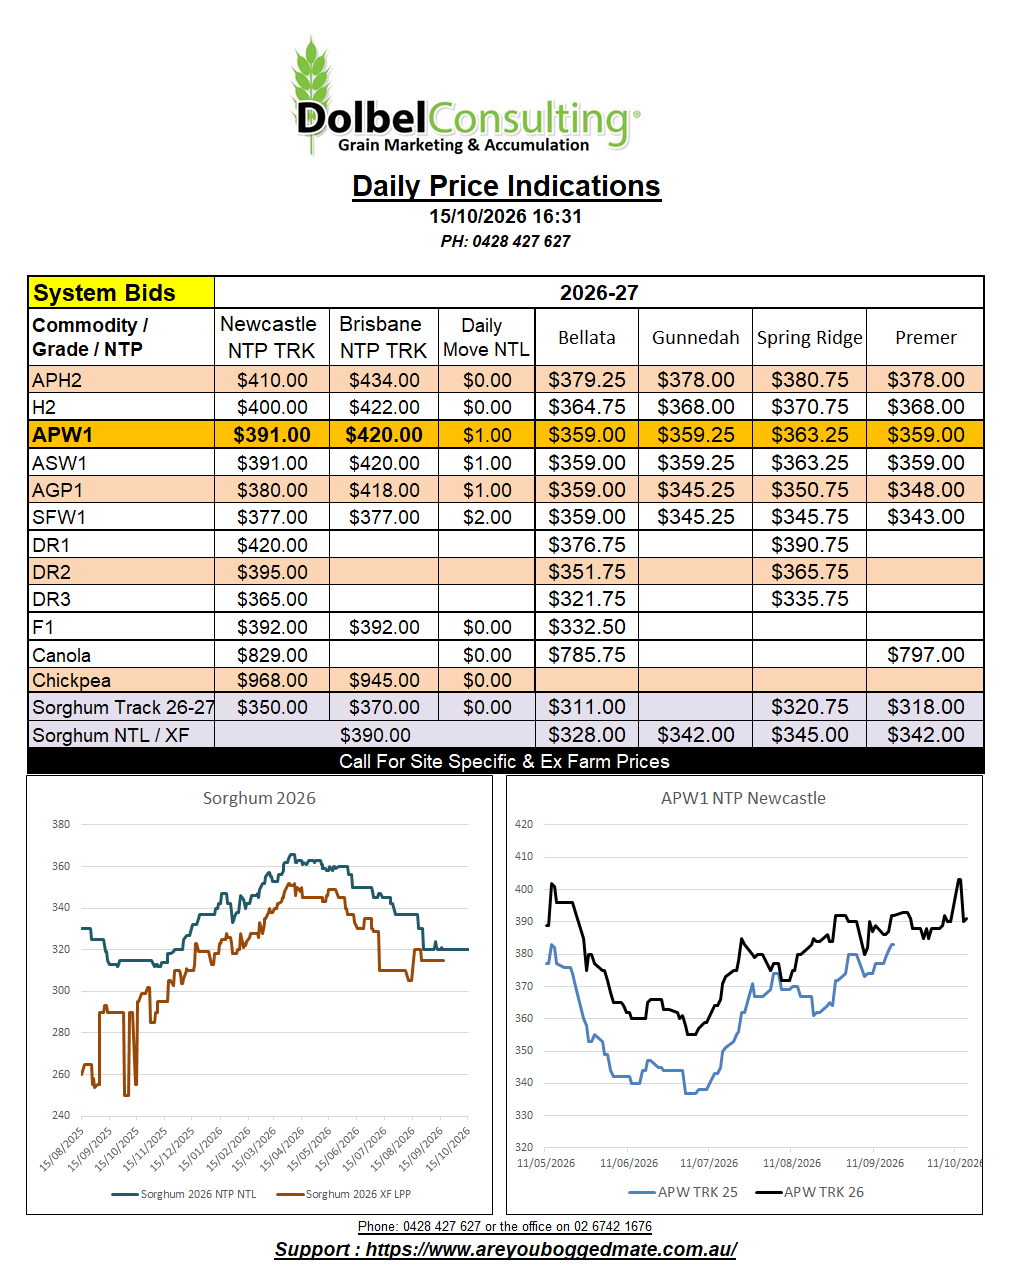
Algeria was said to have picked up wheat from France. With the absence of Black Sea wheat, European exporters seem to be the beneficiaries at this stage. Paris milling wheat futures closed at €244.25/t in the December slot, up €2.25 overnight. Cash values FOB Rouen for 12% milling wheat were a smidge lower compared to yesterdays conversion to AUD. At US$267.50 FOB, French wheat works into the Asian market at roughly US$337.50 C&F. This is actually +US$8.00 over the current grower bids here in NNSW for H2 NTP NTL equivalent. French wheat is also much cheaper than Argie wheat.
The US product is the cheapest into Asia. Leading one to assume that if the Black Sea does not find a resolution in the near term, many buyers will start to flow towards the US market.
In last weeks WASDE we see the “major importers” import demand for wheat reduced by 2.17mt. The list of major importers includes China. If we look at the stocks to use ratio for the major importers, including China, it looks safe, around 47%. Remove China from that list and the stocks to use ratio is reduced to just over 21%. That’s about 2.5 months of stock. Drilling down a little further the data reveals that the SE Asian market, 11.65%, is the tightest of the group once you get over just how tight things are in Nigeria, S:U 5.71% there. Brazil is also tight at 14.8%, this should continue to support the Argentine market. There has been a significant amount of rain across the main wheat producing regions in Brazil over the last month, harvest starts in September there.
With the S:U ratio so tight into SE Asia we should see good demand for Aussie wheat. Current WASDE data has Aussie exports pegged at 23.5mt.