29/10/26 Prices
International
I’ll start by stating the obvious, wheat was hit again last night. All grades of US wheat were lower across all months bar MGEX Dec 2027, but a small gain on the back of just 126 contracts doesn’t shed a lot of light at the end of the wheat tunnel.
Just for the sake of it I like to do the whole CPI adjusted value when things start to look this cheap. Helps put things into perspective and can show just how much better off a consumer might feel buying at this level. Lets look at Dec soft red winter wheat. Say the Dec 2006 slot. Chicago futures were 483c/bu on the 31st of October 2006, the AUD was 76.87USc (AUD$231). We’ll use the CPI that the governments like to talk about, not the real one that normal folk like you and I feel, let’s call it 2.5%. That 483c/bu is now equivalent to 791c/bu, with today’s currency of 70.52 that’s AUD$412 (no basis additions).
My spreadsheet only goes back to 1998, the worst I could find back that far was 224c/bu back in December 1999, 13th of December…. it was a Monday of course. That terrible number of 224c/bu, at today exchange rate is AUD$116.71/t. Using 2.5% pa for inflation, it works out at 917c/bu (AUD$477.78/t) in 2026. So there you have it, like we all didn’t already know. Thanks to not only the increased cost of production, but also the the value of wheat to keep pace with the CPI, we confirm the price wheat is terrible. I should have warned everyone to remove sharp objects from reach before reading this.
US futures pushed lower on the back of news that Russian exports out of the Black Sea may resume soon. A rumor, probably, who knows, it’s not like a fund manager could profit from false news is it….. Anyway… there was a Russian / European (Finland & Norway) phone conversation, the first since July 2025. Reports suggest the 90 minute phone call did not cover in detail the demands of a ceasefire, but did reiterate Russia’s reasoning as to why they are at war with Ukraine, at length, apparently.
In the meantime international governments appear more concerned about controlling free speech than helping to restore free trade.
Domestic
It’s time to talk about the F word….. Freight. With less grain getting delivered to the central storage system and more grain getting booked ex farm or delivered destination, freight arrangements as well as rates will play a crucial role over the next few months. We’re all seeing the “fuel levy” getting applied to freight rates. In the shop the bulk furniture rate varies on almost every delivery. Ranging from 23% to 32% over the last few months. If you are negotiating freight rates be certain you are being quoted the net rate. Not a indicator rate with a variable fuel levy added.
With more traders off loading freight risk to the seller and buying on a delivered basis. It is also important to check freight availability and to book the tonnage and rate with the carrier at the time of contracting.
This isn’t always guarantee, I’ve seen freight companies walk on deals, but depending on your relationship with the carrier it will be a lot better than just hoping to get a carrier at the right rate 10 minutes after your contract gets called up.
I do not broker freight, I can not charge enough to cover my time to broker freight. Brokerage at $2.00/t hardly covers the cost of brokerage these days.
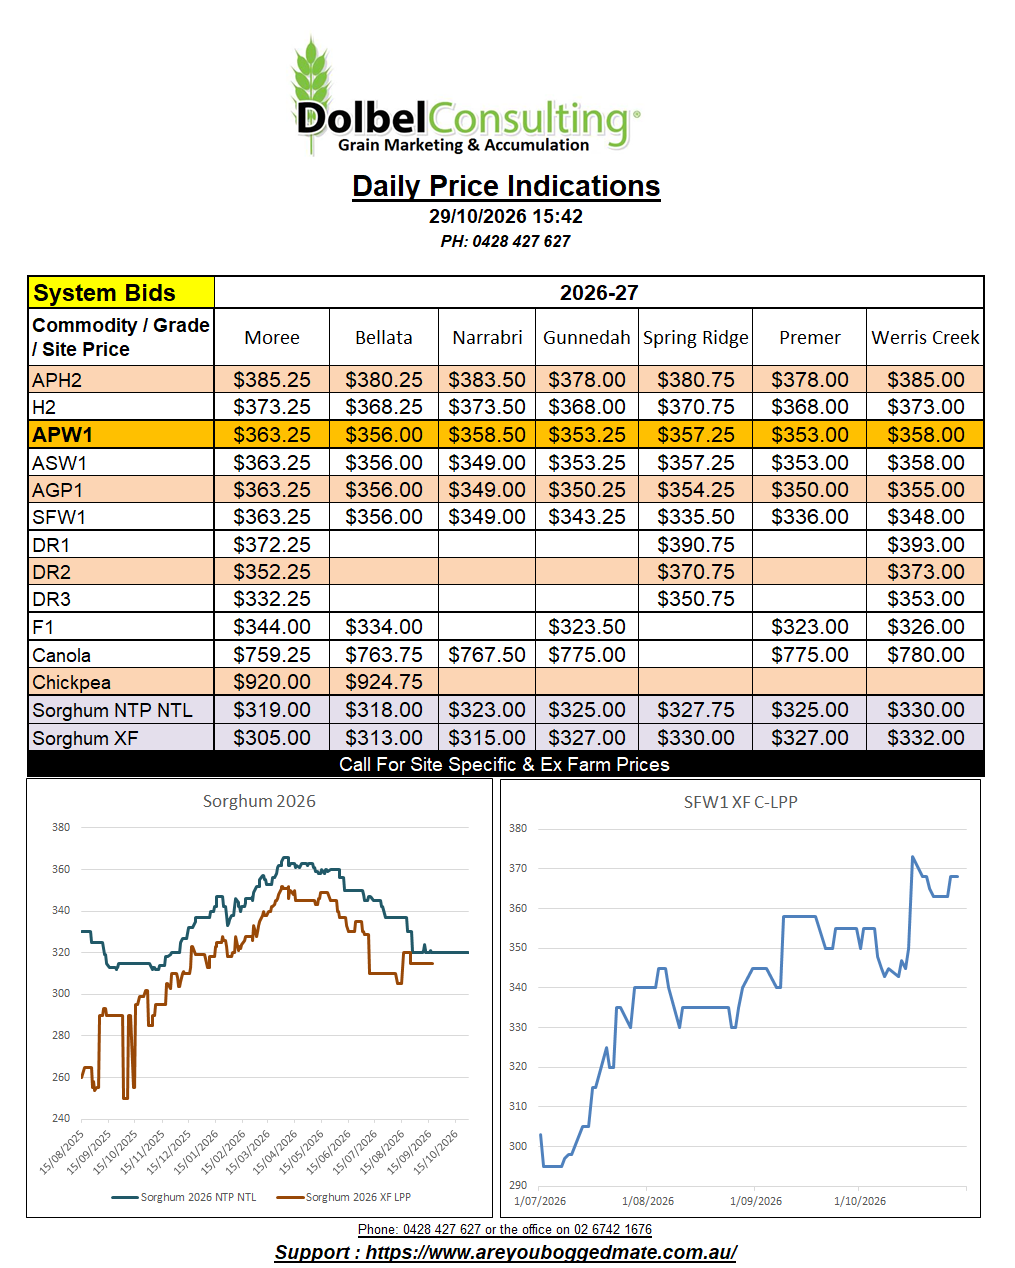
Feed barley was offered at $340 ex farm Gunnedah, bid $325. The public bids are coming in around $350 delivered LPP end user. This makes the $325 number look like a solid bid. Compared to international values local prices are at a premium. Working C&F Chinese values back to an XF LPP value we came up with something closer to $253 / tonne XF LPP yesterday. Keep in mind that Australian feed barley is the cheapest feed barley to China by about AUD$20.00/t at present. Canadian feed barley C&F China, basis LPP is roughly AUD$274 XF equivalent.
Weather
The BOM synoptic chart shows little change in the prediction to yesterday. A high cell moving across SE Australia this morning will direct moist E-NE airflow inland across the eastern states from tomorrow. Priming the interior with moisture and feeding a developing trough line along the NSW / SA border.
It’s this trough line that will produce rain and storms across the eastern wheat belt on Saturday and Sunday. On Saturday morning the trough will deepen, consolidating along the western parts of NSW. A weak low clipping the very far SE of the continent will help push the trough east and across the Riverina on Saturday morning.
The trough will move slowly east during Saturday to be located along the western edge of the NNSW wheat belt in the evening. A band of storms is expected to stretch from roughly Wagga in the south, NW and across SW QLD late Saturday. Storms are expected to become severe around Wagga and east across the high country and towards the SE coast of NSW late on Saturday afternoon and evening.
Here in NNSW storms are expected to become active west of the Newell around Coonamble and Walgett late in the afternoon and early evening. Storms will initially become severe across the SW of the plains and the Upper Hunter as we move into the evening. The trough will be slow moving, possibly spawning another band of storms late in the evening. This second band of storms should produce good falls across the LPP late on Saturday night or early Sunday.
The heavier falls are expected to be south of Spring Ridge, across the Coolah Tops and towards the Upper Hunter. Blackville could see 10-40mm of rain.
more storms are possible on Tuesday the 3rd. Wet track at Flemington.