6/11/26 Prices
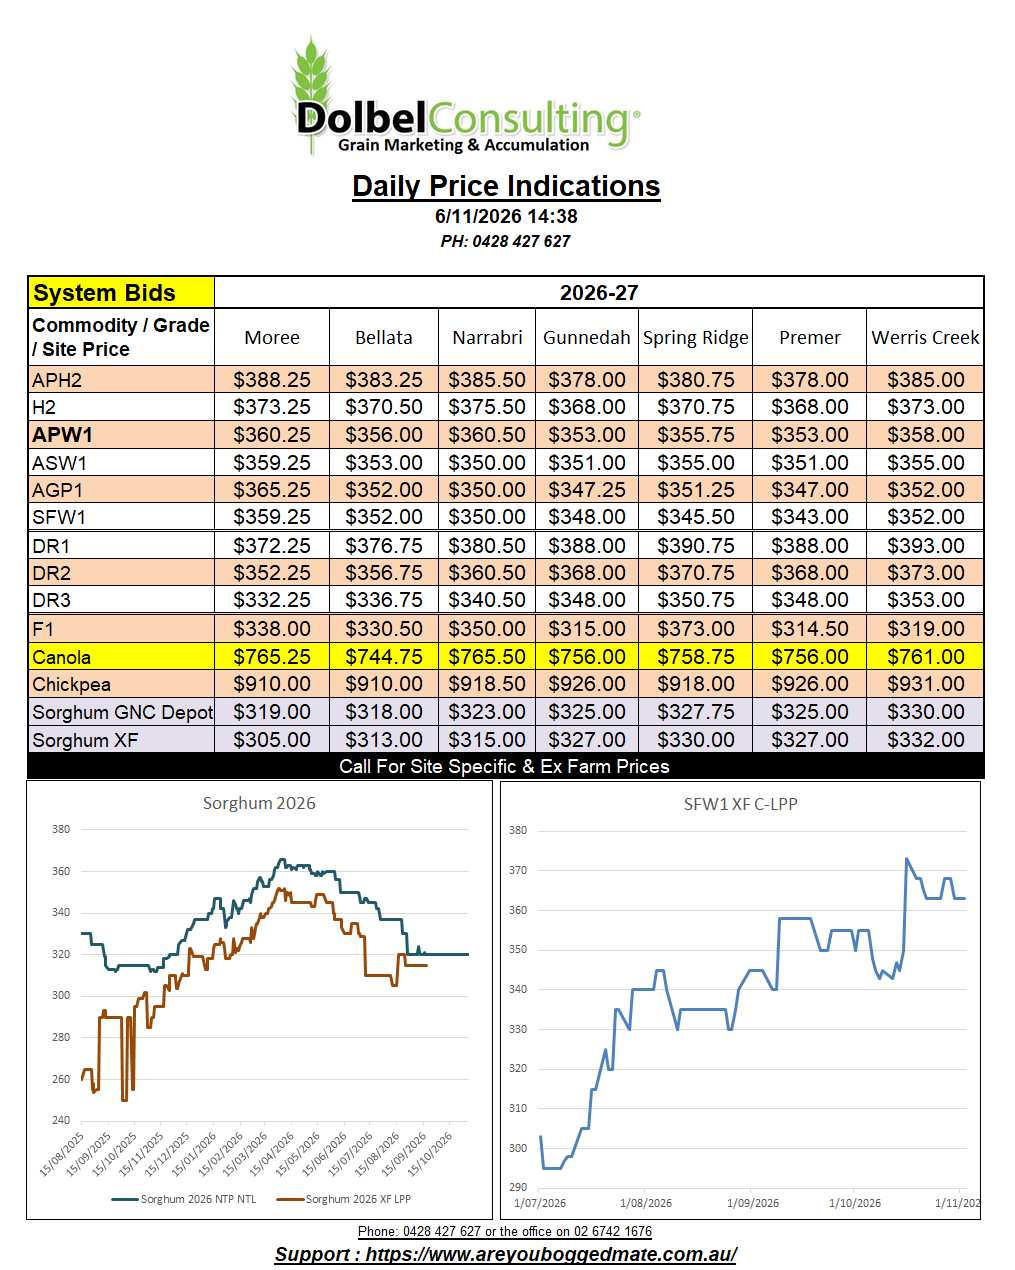
Chicago soft red winter wheat struggled to close higher, it done so in the Dec and March slots but outer months were lower. Hard red winter wheat and spring wheat futures in the US managed to closer higher across all months.
The move wasn’t as much as what we were hoping for, I mean, it’s not like there’s no wheat coming out of Russian or Ukraine Black Sea ports, or that NW NSW and QLD had a drought, or the US harvested their smallest winter wheat crop in ages, or the main wheat producing regions of Brazil were washed out, or China recently expressed interest in buying US wheat, or the weather across the Russian wheat districts is dry has seen less than 10mm of rain over the last 3 weeks, or the Indian monsoon was less than ideal, or there was a 1-100 year drought in France. Oh, sorry, no wait, that all happened.
The trade was generally hoping for a bigger US weekly wheat export sales number than 538kt, less than last weeks yes, and also within the average trade range, but still a little disappointing considering the above paragraph. Well at least the market didn’t move lower like in did in Paris, milling wheat there shed E1.00 nearby.
The comparisons table out of the US Pacific Northwest was generally higher than yesterdays conversions. A nice mix of better US$ FOB values and the softer AUD. The HRWW conversion comparison has gained about AUD$6.29/t day to day, spring wheat roughly +AUD$5.52/t. US milling wheat is still the cheapest milling wheat into Asia bar Russian and Ukraine, if you could get it. The discount to French wheat was eroded a little but it’s still more than US$20.00 cheaper for the Asian consumer to buy US wheat. Argie and Aussie wheat are level pegging into the Asian market, still US$10 to US$20 above French wheat though.
The weaker AUD will help buffer some of the losses across the board in the oilseed market, as may a firmer crude oil market, oil +US$3.66/b Jan.