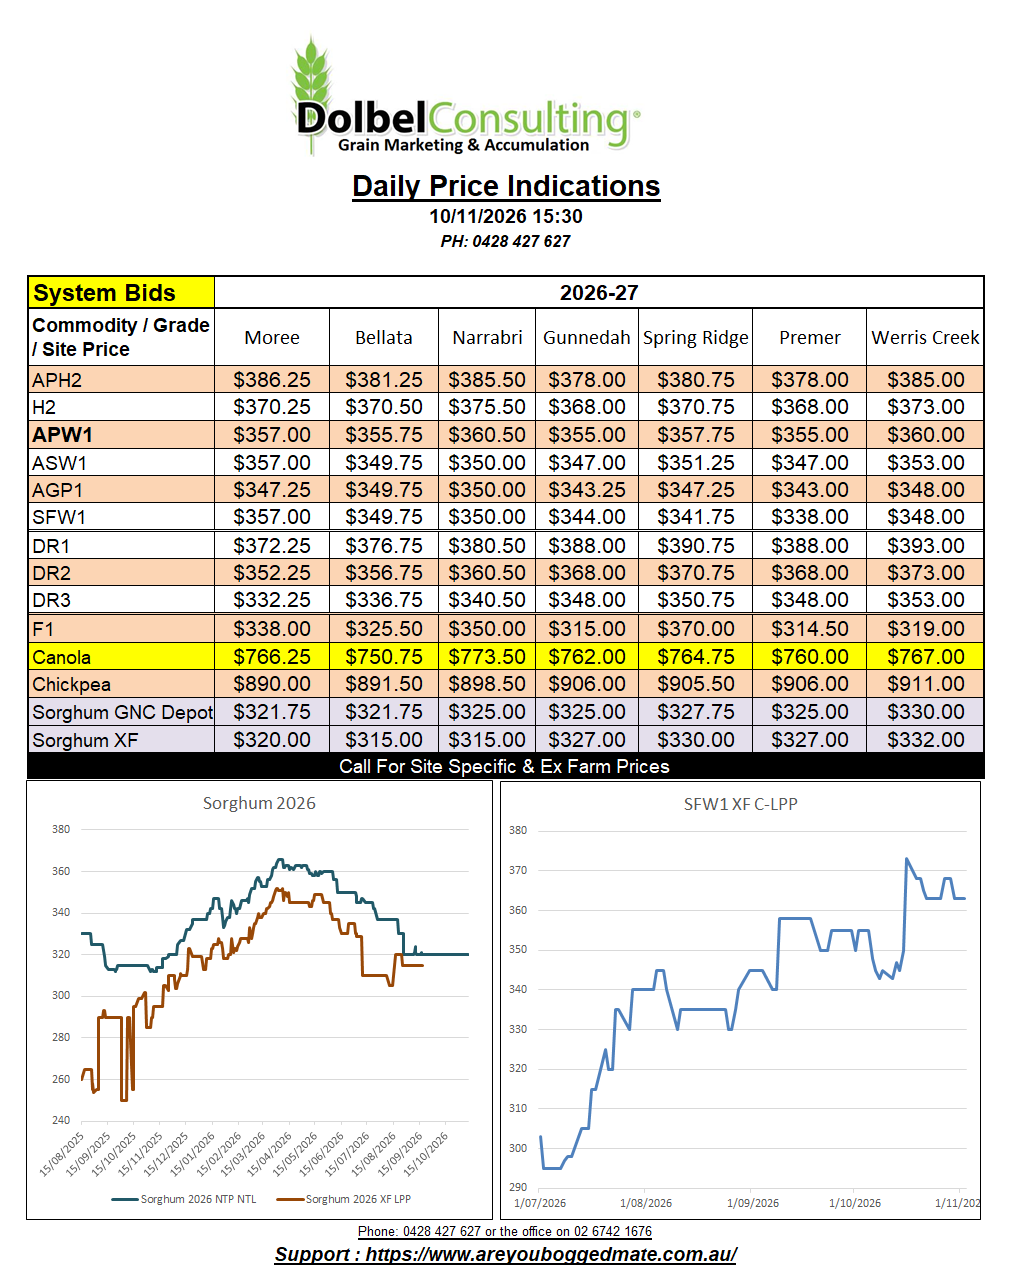
10/11/26 Prices
US wheat futures continued to push lower. The decline in wheat over the last few weeks has been outstanding from a technical perspective, breaching many technical support levels on it’s path to the abys. For a contract to trade lower from an already oversold position, so often is unusual, and to remain technically oversold for 17 consecutive sessions isn’t something we see often.
It doesn’t appear to be a pricing issue. US wheat is cheap and available. Out of the Pacific Northwest into the Asian market the US product is more than US$20.00 cheaper than EU wheat into Asia, and is cheaper than Argie and Aussie wheat. It’s surely not a price problem.
The issue seems to be the carrot that is being held out by values from Russia and Ukraine. At US$194.50 FOB Black Sea, Russian wheat looks exceptionally cheap. But like the carrot being held out in front of the donkey, there’s a very real chance that the consumer may never get to bite into this wheat at this value.
The Black Sea FOB price is so low because can’t be executed. It is reflecting what it costs to execute that wheat from a lot further away. It’s just a carrot.
We have a USDA World Ag Supply and Demand Estimates report out tonight. The punters appeared happy to keep the Chicago wheat product oversold last night. Possibly indicating they are expecting to see world ending stocks for wheat increased in tonight’s report. That’s probably a pretty safe assumption considering that Russia and Ukraine can’t move wheat to export quick enough and the US can’t find buyers to buy at the same volume the buyers would have been buying that Black Sea wheat.
The EU may see ending stocks tighten up, better than expected export sales will play off against lower production there. We may also see further reductions to Brazilian production of wheat, possibly increasing imports from Argentina.
Production in Australia may be reduced due to frosts across the SE, and weather damage across the NWSP but this may not show up until Dec estimates.