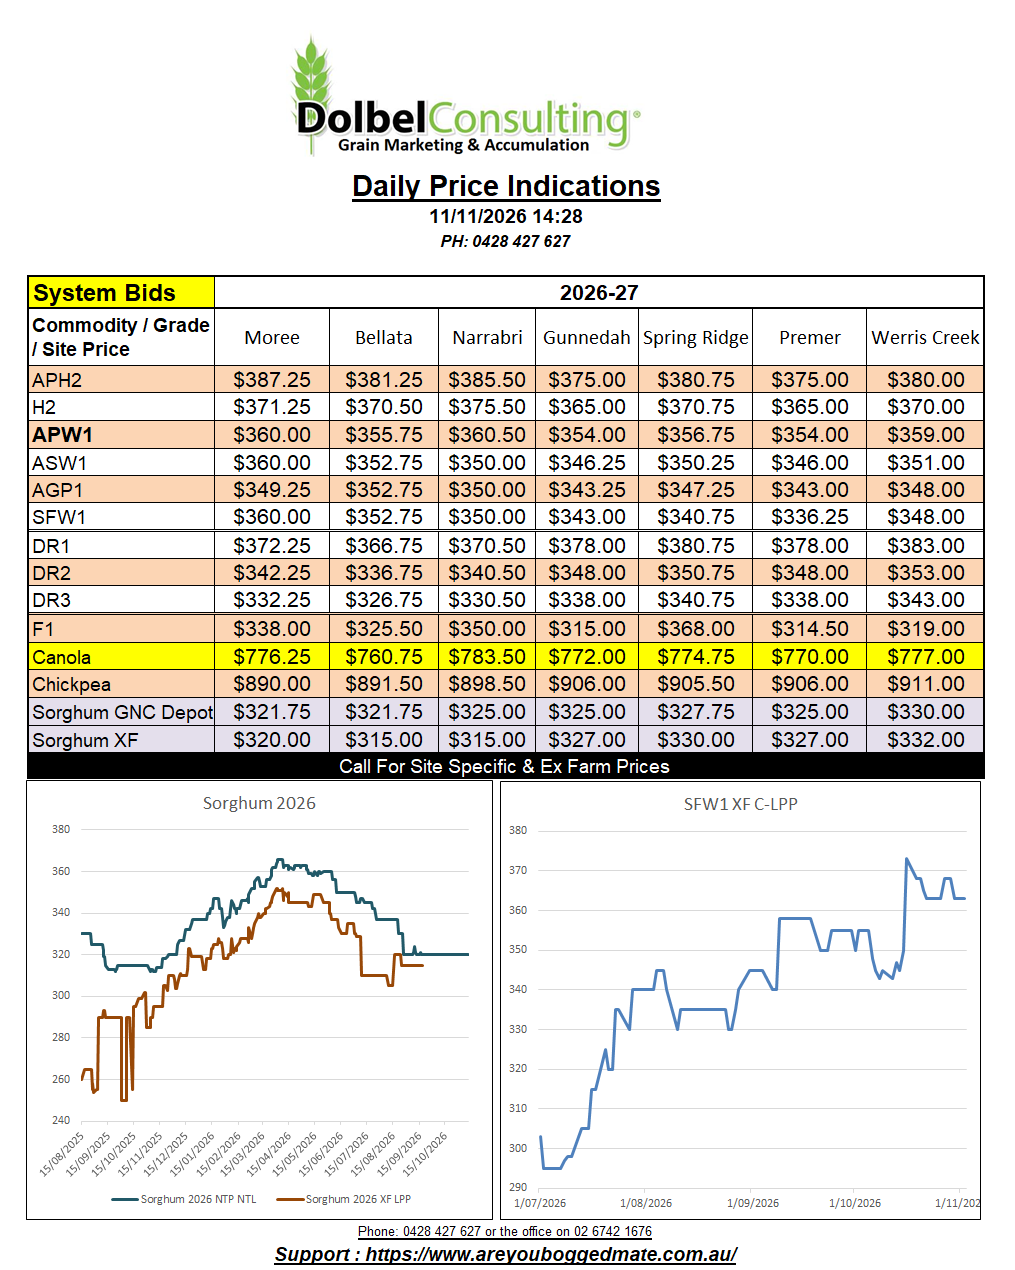
11/11/26 Prices
The USDA released their November World Ag Supply and Demand Estimates report last night. The WASDE had a few adjustments in it for corn and soybeans in the USA relating to yields. This saw some adjustments to state and national production, generally supporting the market. This support spilt over into the wheat futures market.
Last month corn yield estimates in a couple of states were heavily criticised. Later the market discovered the AI modelling used for yield estimates was flawed. The punters had generally expected to see yields for corn reduced in specific states, Nebraska being a key state of controversy. The average corn yield was lowered by just 1.6bu/ha nationally, from 181.2bu/ac (11.37t/ha) to 179.6bu/ac (11.27t/ha).
Onto wheat. The USDA see world wheat ending stocks climbing from last months estimate of 276.04mt to 280.82mt. This ain’t great. In fact not much in this report is great for wheat.
World carry in was increased, world production was increased, world imports were reduced, one positive was that consumption was increased slightly, international exports were reduced and ending stocks were increased. There’s no part of that that is bullish wheat short to mid term.
The worse bit is that the majority of increases in ending stocks are in the major exporters, up 3.41mt. Argentina +1mt, Australia +0.21mt, Ukraine +1.2mt and Russia +1mt. The trade had expected to see Black Sea stocks increase, but the others not so much. Interesting to note the USDA kept Brazilian wheat imports at 5.8mt. That may well turn out to be a little low after rain reduced the yield and quality there.
The reduction on imports were across the major consumers, down 1.1mt, the bulk of that reduction is in the Middle East, the major consumers of Black Sea wheat. SE Asian projected imports were actually forecast to increase by 200kt to 31.6mt.
An increase from 15mt to 15.8mt for wheat production in Kazakhstan is a little sceptical too. Some may argue +1.5mt to 32.5mt for Australia is high too.